About this episode
Julia Reinaud has a tidy way of describing the problem. It is not a sprint, she says, and it is not even a marathon. It is a relay. Every time a project moves forward, someone has to take the baton: an offtaker, a lender, an infrastructure fund, a permitting authority. And too often the baton gets dropped.
That is the shape of the conversation. Julia is Senior Director, Europe at Breakthrough Energy, where she has spent eight years building the organisation’s European partnerships, and she arrives with a specific complaint about how the sector talks about itself. We celebrate the first-of-a-kind project, she argues, when the thing that actually changes a market is the tenth and the fifteenth, the point at which a clean technology stops being a clean technology and becomes an ordinary industrial asset. First-of-a-kind is not the destination. It is one leg of the relay.
Underneath that is a diagnosis of why the handovers fail. A company that has proven its technology needs capital of a size and shape that neither venture nor infrastructure will provide: too large and too project-like for venture, too unproven for the project finance market that wants a track record the technology has not had time to build. Julia calls it a bridge you have to wait for. And while it is being waited for, one company is asked to carry technology risk, construction and operating risk, market risk and policy risk simultaneously, on a single balance sheet, while most of the benefits its project creates, lower emissions, resilience, energy security, domestic industrial capacity, accrue to a system that is not paying for them.
Her answer is not more money. It is structures that solve for the specific risk in front of them. Revenue risk is a contract for difference, an offtake, or public support for the premium. Technology and construction risk is catalytic capital, guarantees, milestone-based grants. Infrastructure and permitting is not a financing problem at all, it is a coordination and speed problem, and no amount of capital fixes it. The European partnership she helped build with the European Commission and the European Investment Bank is the worked example.
The most portable part of the episode is her list of five non-negotiables for anyone designing this kind of programme. Public and catalytic capital deliberately designed to crowd private capital in rather than out. Demand-side tools, because companies need customers rather than grants. The discipline to plan for the nth of a kind before the first one is finished. Policy and permitting that make building easier rather than harder. And discipline on cost and scale, which is the one she presses hardest: you back a company because its technology has a path to being cheap and large, not because it is innovative.
For the Australian listener the last third is the payload. Julia knows the country, and her read is that it looks more like Europe than Australians think, a federation where the states matter enormously, with the crucial difference of natural resources. She names five places deployment could start: long-duration storage as coal retires, industrial heat electrification and thermal storage, livestock methane, critical minerals, and off-grid and remote power. And she gives one piece of advice above the others, which is to stop making it unnecessarily hard. Get ARENA, the CEFC, Future Made in Australia and the state programmes into a single room and look at the financing landscape from the entrepreneur’s side of the table, because the alternative, the one she has watched in Europe, is a policymaker who agrees the project should be built and then explains that the offtake support is another department and the permitting is another level of government.
She closes with what she has seen work: Project SkyPower, where fifteen CEOs from across the European e-SAF value chain, plus airports, engineering contractors, banks, the Commission, member states and finance ministries, were put in one room and kept there until the economics were on the table. It produced a double-sided auction pilot, now being taken forward by the European Commission, in which producers compete to supply at the lowest price over ten to fifteen years and airlines bid on the demand side, with public money bridging the gap. Her point is not the mechanism. It is that nothing about it required an invention. It required the people who each thought the problem belonged to someone else to be in the same room.
About the guest
Julia Reinaud is Senior Director, Europe at Breakthrough Energy, which she joined in 2018. She has spent more than two decades working on climate and energy with a consistent focus on decarbonising heavy industry. She began her career as an analyst at the International Energy Agency, working on carbon markets, trade and competitiveness. She then founded and led the Institute for Industrial Productivity, advancing industrial energy efficiency across China, India, the United States and Europe, and afterwards created and co-led the industrial innovation for competitiveness programme at the European Climate Foundation. At Breakthrough Energy she has built the organisation’s European partnerships, including the fund established with the European Commission and the European Investment Bank. She sits on the board of the Mission Possible Partnership and is a member of the Mission Innovation Technical Advisory Group. She holds a PhD with distinction in economics and industrial strategy from University Paris Dauphine, and is based in Paris.
Breakthrough Energy was founded by Bill Gates at the Paris COP in 2015 and is a global platform working to accelerate clean energy innovation and build the industries and companies the transition needs. It invests across what Julia calls the three Ds, discovery, development and deployment, through Breakthrough Energy Ventures and its growth funds, which have backed well over a hundred companies; it convenes the customers, investors, governments, offtakers and industrial partners those companies need around them; and it works on policy and market design, on the basis that the barrier to a clean technology is often a standard, a permit or a piece of infrastructure rather than the technology itself.
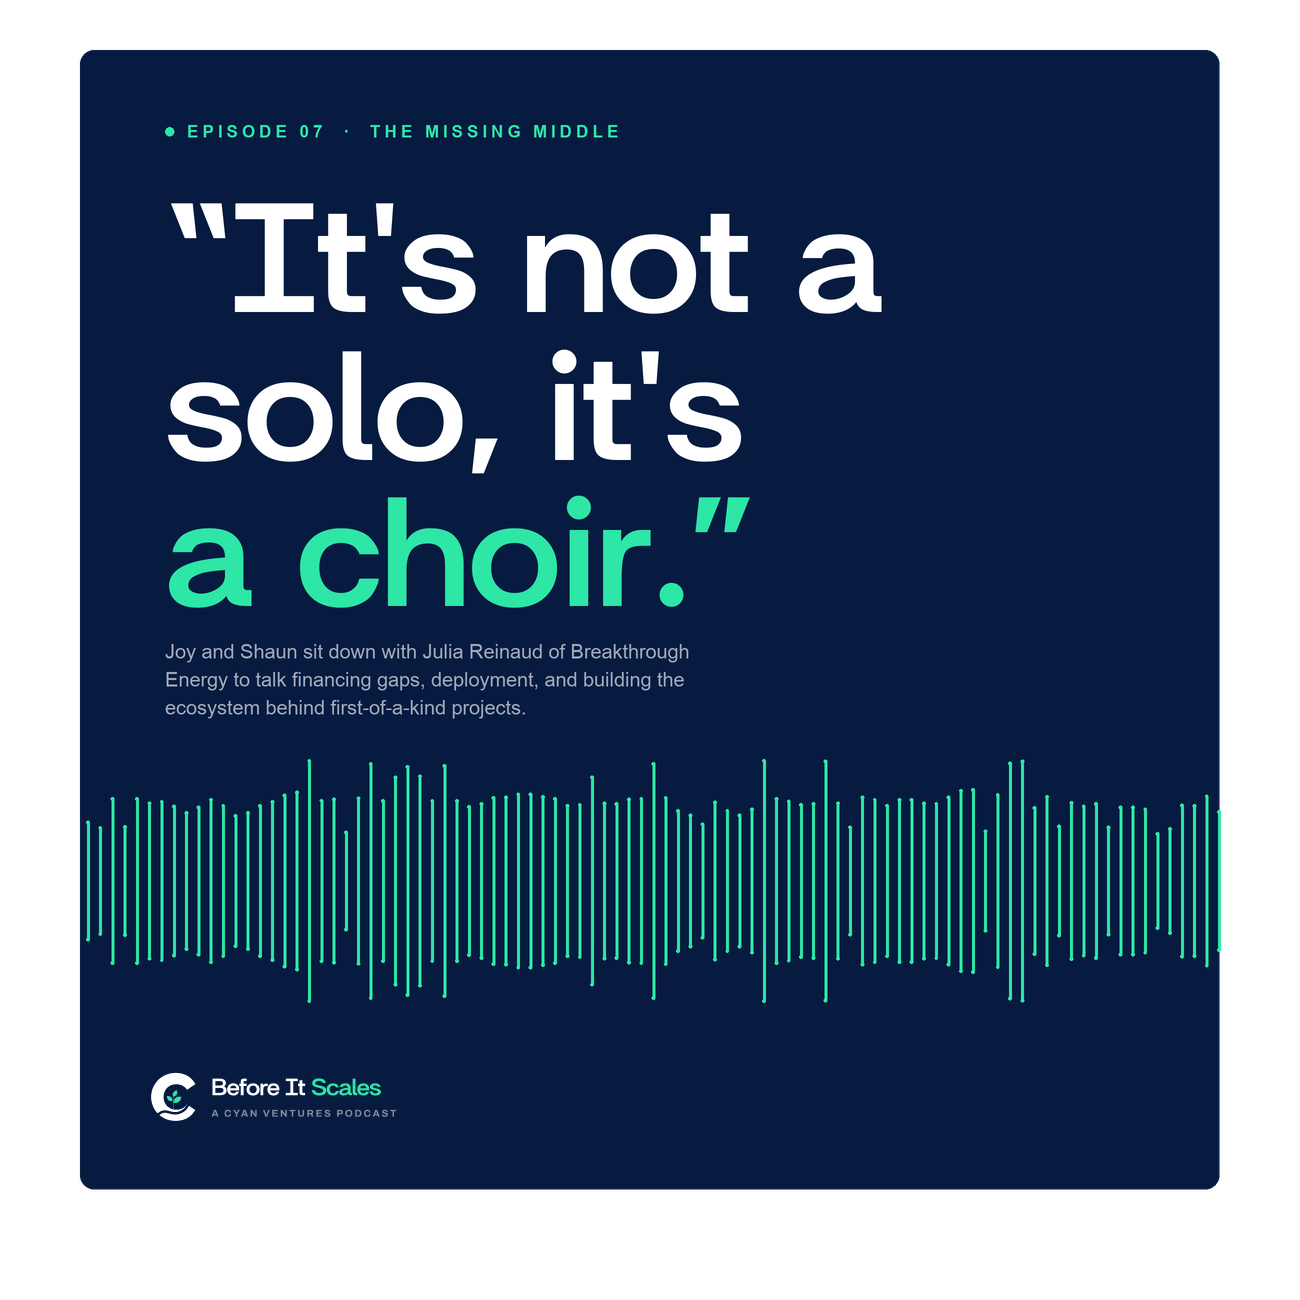
”It is not a sprint, it is a marathon. But I would add to that: it also needs to be a relay. Every time you are passing the baton to someone else, that person needs to support you, and that might be an offtaker or it might be another investor. The big challenge is that the first-of-a-kind is not the destination. It is really the nth of a kind. And too often that baton gets dropped. It is not going to be just the CEO who holds that baton. It needs to be an entire ecosystem.
Julia Reinaud
We cover
- The thread through the career: the IEA, the Institute for Industrial Productivity, the European Climate Foundation
- From analysing the transition to moving money into it
- What she believed early on that turned out to be wrong
- Abundance, and why prioritisation is the new discipline
- What Breakthrough Energy does, and why it is a choir rather than a solo
- The deployment era, and why TRL 9 is not the finish line
- The relay, and the baton that gets dropped
- The 12 Keys to Scaling Up, and the ARPA-E test
- Four kinds of risk on one balance sheet
- Portfolios rather than projects, and industrial strategy rather than a cleantech play
- The missing middle, and why the market will not fill it
- Structures that solve for the specific risk
- The EU partnership, and where it stops working
- Marrying a public bank and a venture fund
- Five non-negotiables
- Australia’s role, and five places deployment could start
- Do not make it unnecessarily hard for entrepreneurs
- Project SkyPower, and the double-sided auction
- Simplicity, speed and scale